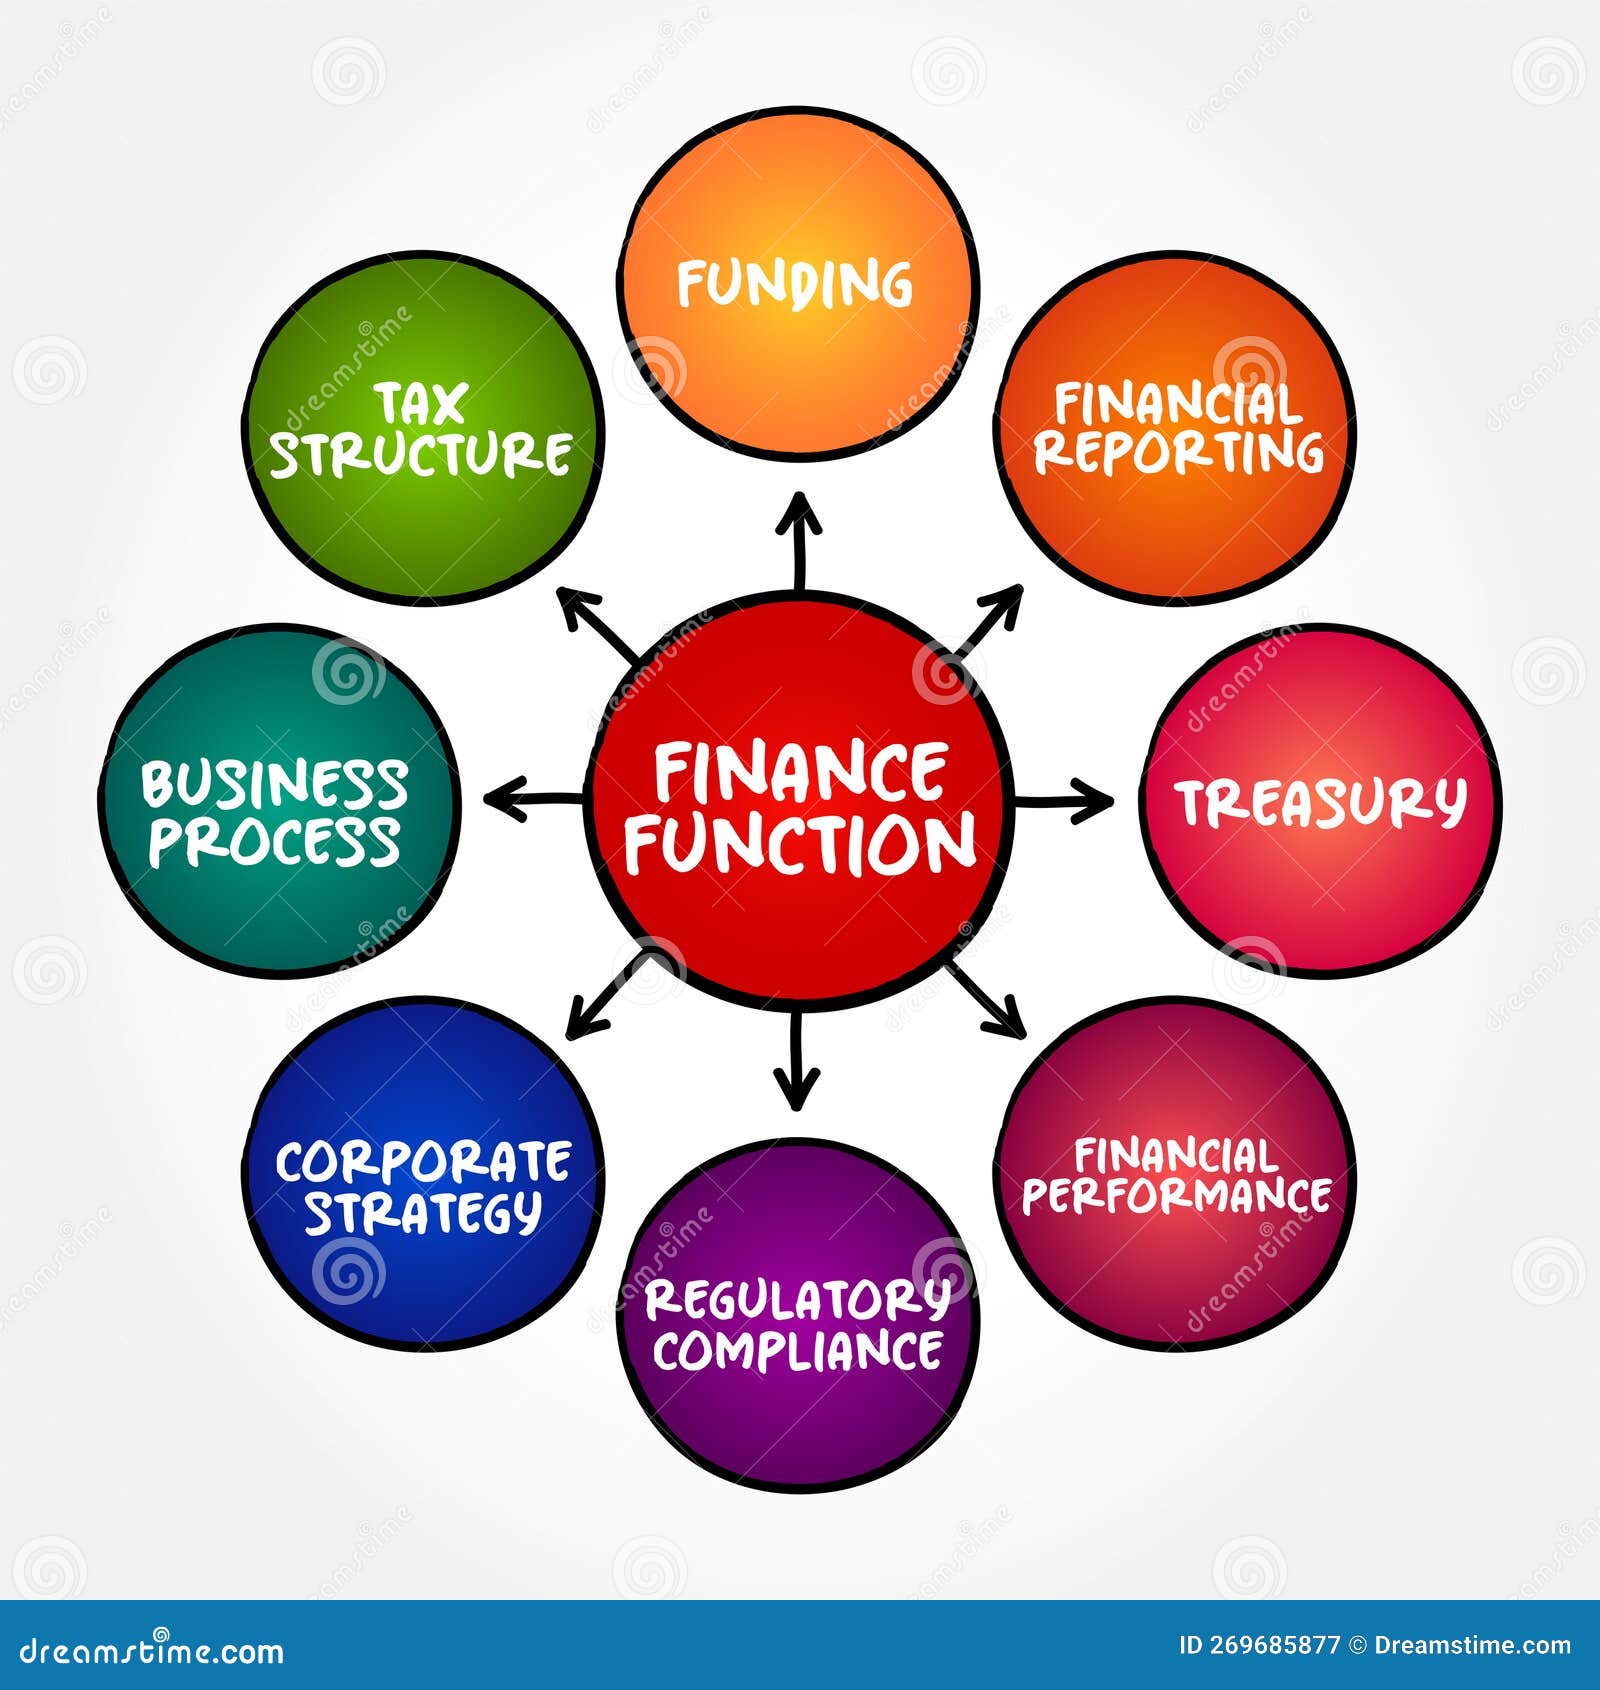
Alternative financial service providers fill critical gaps in regional markets that traditional commercial banks often overlook. In growing university hubs like Statesboro, Georgia, companies like World Finance operate as key components of the micro-economy by extending personal installment loans, tax preparation, and short-term credit options to residents who might not qualify for standard banking products. Understanding how these specialized financial institutions interact with local commerce requires looking past corporate balance sheets and examining day-to-day consumer credit flows in Bulloch County.
Statesboro's economic framework relies heavily on a unique blend of student populations from Georgia Southern University, retail trade centers, and surrounding agricultural enterprises. Financial service offices situated along major corridors like South Main Street or Fair Road provide immediate liquidity options for households facing unexpected expenses. While traditional institutions focus on long-term mortgages and commercial lending, alternative lenders process smaller consumer loans, bridging cash flow gaps for residents and local service workers.
The Alternative Credit Niche in Bulloch County
Standard commercial banking models depend on strict underwriting criteria, high credit score thresholds, and traditional collateral. Many wage earners, gig economy workers, and college students lack the credit history required to secure traditional bank loans. Alternative lenders step into this specific niche by offering signature loans and personal installment options that require predictable repayment structures rather than pristine credit files.
In a regional market shaped by seasonal student populations, cash flow can fluctuate significantly for local retailers and service providers. When part-time workers or young professionals encounter emergency car repairs or medical bills, consumer installment loans prevent minor financial crunches from compounding into evictions or utility shutoffs. This availability of immediate capital keeps consumer spending active within the local retail and service sectors, directly supporting neighborhood storefronts. For another perspective on this event, see the latest update from Reuters.
Consumer Lending Dynamics and Household Budgets
Managing personal debt in a mid-sized southern city involves balancing fixed living costs against regional wage averages. Personal loans carry higher interest rates than traditional bank products because lenders assume higher unsecured risk. Borrowers must evaluate whether short-term liquidity justifies the total cost of credit over a twelve-to-twenty-four-month repayment schedule.
Responsible borrowing habits dictate that installment loans should serve specific, non-recurring needs rather than chronic budget shortfalls. Local consumer advocates encourage borrowers to review amortization schedules carefully, ensuring that monthly payments fit comfortably within established household budgets. When used strategically to consolidate high-interest debt or manage unavoidable emergencies, these credit products help consumers stabilize their financial standing.
Interaction with Small Business and the Regional Workforce
Beyond direct consumer lending, the physical presence of financial service branches contributes to local commercial real estate and job creation. Branch offices lease commercial storefronts, hire local staff, and purchase administrative services from regional vendors. Office teams manage compliance, customer service, and local marketing initiatives, integrating directly into the Bulloch County business community.
Small business owners frequently rely on alternative financial products during initial startup phases or seasonal slow periods when commercial lines of credit remain out of reach. Sole proprietors, independent contractors, and local service operators sometimes utilize personal or small business installment financing to purchase inventory, repair equipment, or cover payroll during unexpected slumps. This flexible capital access supports micro-entrepreneurship across Bulloch County, keeping independent shops operational.
Digital Integration and Modern Financial Access
The consumer finance sector continues to shift away from purely brick-and-mortar interactions toward hybrid digital models. Modern platforms allow borrowers to manage applications, review loan documents, and execute payments through secure web portals and mobile applications.
- Online Account Management: Customers track payment due dates and remaining balances without visiting a physical branch.
- Automated Repayment Systems: Direct debit setups reduce missed payment risks and protect consumer credit scores.
- Enhanced Data Security: Encrypted platforms safeguard sensitive personal and financial data during digital transactions.
This technological evolution reduces administrative overhead for regional operators while giving consumers faster access to credit decisions. For busy working families and university students balancing class schedules with part-time jobs, digital accessibility streamlines the entire borrowing process.
Frequently Asked Questions
What types of loans do alternative financial offices offer in Statesboro?
Most locations specialize in personal installment loans, signature loans requiring no collateral, and tax preparation assistance. These products provide fixed lump sums repaid through structured monthly increments over set terms.
How do installment loans differ from payday loans?
Installment loans spread repayment across multiple months or years with predictable, scheduled payments. Payday loans typically require full repayment by the borrower's next paycheck, often carrying significantly higher fee structures and shorter durations.
Do alternative lenders report to major credit bureaus?
Yes. Responsible lenders report payment histories to major credit reporting agencies. Making consistent, on-time payments toward an installment loan can help individuals build or repair their credit scores over time.
What should borrowers consider before taking out a personal loan?
Borrowers must review the annual percentage rate, total repayment amount, and monthly installment size relative to their monthly income. Creating a strict repayment budget ensures the debt remains manageable without straining essential living expenses.



