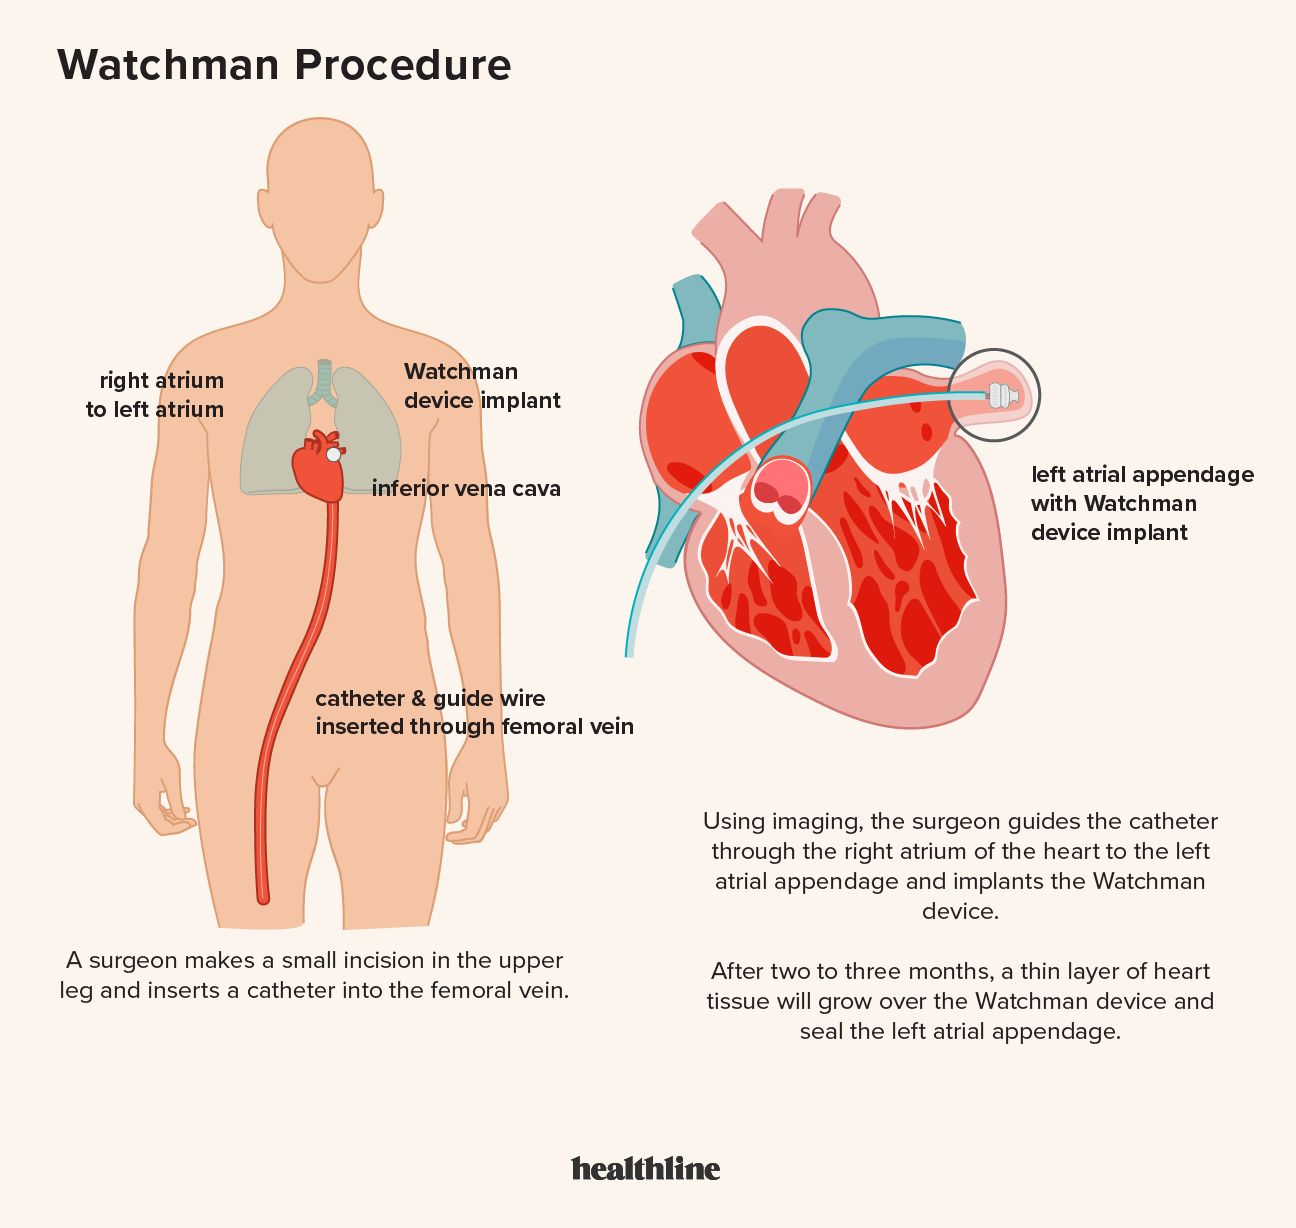
When you're facing a left atrial appendage closure procedure to reduce stroke risk from atrial fibrillation, the financial side of things can feel overwhelming. The Watchman device cost typically ranges from $22,000 to $30,000 for the hardware alone, but that's only part of the overall bill. Total hospital charges, physician fees, and anesthesia push the comprehensive procedure cost much higher, often landing between $25,000 and $40,000 depending on your facility and region.
Navigating these numbers requires looking past sticker prices and understanding how health insurance, Medicare, and out-of-pocket maximums interact with your specific cardiac care. Let's break down what you'll actually pay, what insurance covers, and how to avoid surprise medical bills.
Understanding the Total Price Breakdown
The total cost of a Watchman procedure isn't a single flat fee. It's a combination of several distinct medical services billed by the hospital, the cardiac electrophysiologist, and the anesthesiologist.
- The Implantable Device: The hardware itself accounts for a major portion of the hospital's supply costs. Newer iterations, such as the Watchman FLX, carry high manufacturer pricing.
- Physician and Surgeon Fees: Your cardiologist or electrophysiologist charges separately for the catheterization procedure, transesophageal echocardiography guidance, and post-implant evaluation.
- Facility and Operating Room Fees: Hospitals charge hourly or flat rates for the catheterization lab, nursing staff, sterile supplies, and recovery room monitoring.
- Anesthesia Services: General anesthesia or conscious sedation requires dedicated anesthesia personnel and medications.
Insurance Coverage and Medicare Guidelines
Most major commercial health insurance plans and Medicare cover the Watchman procedure, provided you meet strict medical necessity criteria. Medicare policy generally requires documented non-valvular atrial fibrillation, an increased risk for stroke, and a compelling rationale for seeking an alternative to long-term oral anticoagulants like warfarin.
If you have traditional Medicare (Part A and Part B):
- Part A covers inpatient hospital stays, room, and board if you're admitted overnight.
- Part B covers 80% of the Medicare-approved amount for the physician's services and outpatient surgical fees after you meet your annual deductible.
- Medigap (Secondary Insurance): Supplemental policies often pick up the remaining 20% coinsurance, greatly reducing your personal out-of-pocket liability.
For patients with private or employer-sponsored insurance, your out-of-pocket costs depend entirely on your deductible, copays, and annual out-of-pocket maximum. Review your policy's pre-authorization requirements carefully, as skipping prior authorization can lead to claim denials.
Hidden and Follow-Up Expenses to Anticipate
Budgeting for a medical procedure means looking beyond the day of surgery. You'll need to account for follow-up care that ensures the device is healing correctly.
- Post-Procedure Imaging: Doctors require follow-up transesophageal echocardiograms (TEE) or cardiac CT scans at 45 days and six months post-implant to confirm proper closure and tissue growth over the device.
- Medication Costs: You'll typically take blood thinners or antiplatelet drugs (such as aspirin and clopidogrel) for a specific window after the procedure until healing is confirmed.
- Cardiology Consultations: Routine check-ins with your heart specialist add regular copays to your yearly medical expenses.
According to guidelines from the American College of Cardiology, patient selection and post-implant management are critical to ensuring both clinical safety and long-term cost-effectiveness.
How to Minimize Your Financial Burden
If you're worried about out-of-pocket expenses, don't wait until the bill arrives to take action. Hospitals and device manufacturers have dedicated financial navigators who deal with these exact scenarios every day.
- Request a Detailed Estimate: Ask the hospital billing department for a written pre-service estimate detailing expected charges based on your specific insurance network.
- Contact Patient Financial Services: Many medical centers offer financial assistance programs, sliding-scale adjustments, or interest-free payment plans for patients who qualify.
- Verify Network Status: Ensure your electrophysiologist, the hospital facility, and the anesthesiologist are all in-network for your health plan to prevent surprise out-of-network billing.
For additional resources on understanding your rights regarding medical billing and insurance appeals, visit Healthcare.gov.
Frequently Asked Questions
Does insurance cover the Watchman device entirely?
Not always. While insurance or Medicare typically covers a major percentage of the procedure when medically necessary, you are still responsible for your annual deductible, copays, and coinsurance unless you have robust supplemental coverage.
What is the recovery time and does it affect costs?
Most patients go home the same day or the following morning. Shorter hospital stays help keep room and board charges down, though recovery at home requires adhering strictly to prescribed medications and activity restrictions.
Can I negotiate my hospital bills after the procedure?
Yes. If you receive a large balance bill, contact the hospital's billing advocate immediately. You can often negotiate settlement amounts or set up structured monthly payment plans without interest.
Are there alternative procedures that cost less?
Other stroke-reduction strategies exist, such as pharmaceutical blood thinners or surgical LAA ligation during open-heart surgery, but costs vary wildly based on your unique health profile and long-term medication needs. Your cardiologist can help weigh clinical benefits against financial realities.



