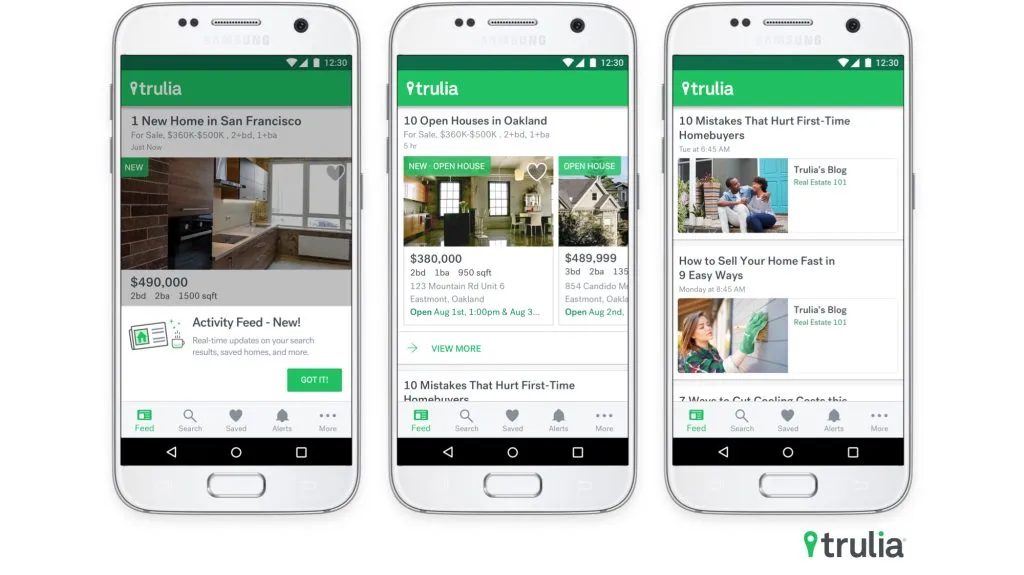
Navigating real estate listings requires more than just scrolling through endless property photos. When you look for a trulia house for sale, you aren't just examining square footage or bedroom counts; you are evaluating an entire ecosystem that includes neighborhood safety, school ratings, local commute times, and realistic financial planning. Master platforms like Trulia by learning how to isolate core data from market noise, utilize interactive map overlays effectively, and approach negotiations with verified local market trends.
Real estate search intent typically falls into two categories: active buyers trying to secure a property before competition spikes, and market researchers assessing neighborhood value trajectories. To get ahead, you need a systematic framework that turns raw digital listings into actionable intelligence.
Navigating Property Listings and Core Filters
Standard keyword searches often overwhelm users with thousands of irrelevant properties. Refining your search parameters from the start saves hours of wasted effort and prevents fatigue during the home search cycle.
- Boundary Drawing: Instead of searching an entire metropolitan area, use custom polygon tools on the map interface to circle specific pockets, school districts, or even individual blocks you prefer.
- Layer Overlays: Turn on heatmaps for crime, schools, and commute times before falling in love with a house layout. A cheap house loses its appeal quickly if the morning commute takes ninety minutes or local safety metrics trend downward.
- Property Type Nuances: Distinguish between single-family detached homes, townhouses, and condos. Condos and townhouses carry monthly homeowner association (HOA) fees that directly alter your monthly debt-to-income ratio.
Filtering effectively means knowing what to ignore. Filter out properties pending sale or under contract unless you want backup status notifications. Focus purely on active inventory that matches your financial pre-approval limits.
Decoding Financial Metrics and Hidden Costs
House hunting fails when buyers focus exclusively on the listing price rather than the total cost of ownership. A comprehensive financial review protects you from buying a house that stretches your monthly budget too thin.
Property taxes vary wildly by county and municipality. A home listed at $300,000 in one tax district might carry double the annual property tax burden of an identical home ten miles away. Factor in homeowners insurance, municipal utility costs, and estimated maintenance reserves—typically budgeted at one percent of the home's value annually.
- Down Payment Realities: Putting down less than twenty percent typically triggers private mortgage insurance (PMI), which adds to your monthly overhead without building equity.
- Interest Rate Fluctuations: Run calculations using current mortgage rates to see how a minor rate shift impacts your monthly principal and interest.
- Break-Even Horizon: If you plan to move within three to four years, closing costs on buying and selling can wipe out any equity gains. Ensure your timeline matches the investment.
You can review current lending standards and consumer resources directly through the Consumer Financial Protection Bureau to understand your rights and loan disclosures.
Utilizing Neighborhood Insights and Local Data
A house sits inside a community, and that community dictates your daily quality of life and future resale value. Relying solely on listing descriptions leaves out critical context about local infrastructure changes, commercial developments, and neighborhood demographics.
Examine resident reviews and local insights provided on mapping platforms. Real residents often mention recurring noise issues, parking restrictions, or seasonal traffic bottlenecks that photos hide. Check local municipal planning boards for upcoming zoning changes, road expansions, or commercial builds nearby that could obstruct views or increase noise levels.
For broader housing market statistics, economic indicators, and national mortgage trend reports, consult the U.S. Department of Housing and Urban Development to gauge broader macroeconomic shifts affecting inventory levels.
Step-by-Step Approach to Touring and Making an Offer
Once you identify potential properties online, transition your strategy to physical inspections and data verification. Moving from digital search to an active offer requires discipline.
- Schedule Multiple Visits: Visit a shortlisted home at different times of day—once during a weekday morning commute, and once on a Friday or Saturday night to gauge neighborhood noise and activity levels.
- Inspect the Infrastructure: Check water pressure, test light switches, look for water stains in ceilings or basements, and examine the age of the roof and HVAC system.
- Review Comparable Sales: Look at recent sales of similar homes within a half-mile radius over the last three months to determine if the asking price aligns with actual market value.
- Draft a Contingent Offer: Include home inspection contingencies and financing clauses to protect your earnest money deposit if structural defects or appraisal shortfalls emerge.
Common Mistakes to Avoid During Your Search
First-time and seasoned buyers alike often fall into predictable traps that complicate transactions or lead to buyer's remorse.
- Waiving Inspections: In competitive markets, some buyers waive home inspections to make their offer look attractive. This gamble can leave you with tens of thousands of dollars in hidden structural or plumbing repairs.
- Maxing Out Pre-Approval: Just because a bank approves you for a specific loan amount doesn't mean your monthly budget can comfortably handle it alongside other living expenses.
- Ignoring Future Resale Factors: Buying a house right next to a busy highway or under a flight path might save money today, but it makes selling the property down the road significantly harder.
Frequently Asked Questions
How accurate are online home valuation estimates?
Online valuation tools provide a helpful baseline using public records and recent local sales data, but they cannot account for interior upgrades, deferred maintenance, or unique architectural features. Always rely on a professional appraisal or comparative market analysis from a licensed local agent for pricing accuracy.
Should I get pre-approved before browsing homes for sale?
Yes. Securing a mortgage pre-approval letter proves to sellers that you are a serious buyer with verified purchasing power. It also helps you move quickly when a desirable property hits the market.
How do I handle multiple-offer situations?
When competing against other buyers, clean contract terms often matter as much as the purchase price. Offering flexible closing dates, minimizing contingencies, and providing a larger earnest money deposit can strengthen your position without necessarily raising your purchase price.
What is the difference between a buyer's agent and a listing agent?
A listing agent represents the seller and has a fiduciary duty to secure the highest price and best terms for them. A buyer's agent represents your interests as the purchaser, helping you navigate negotiations, schedule inspections, and evaluate fair market value at no direct out-of-pocket cost to you in most standard commission structures.


