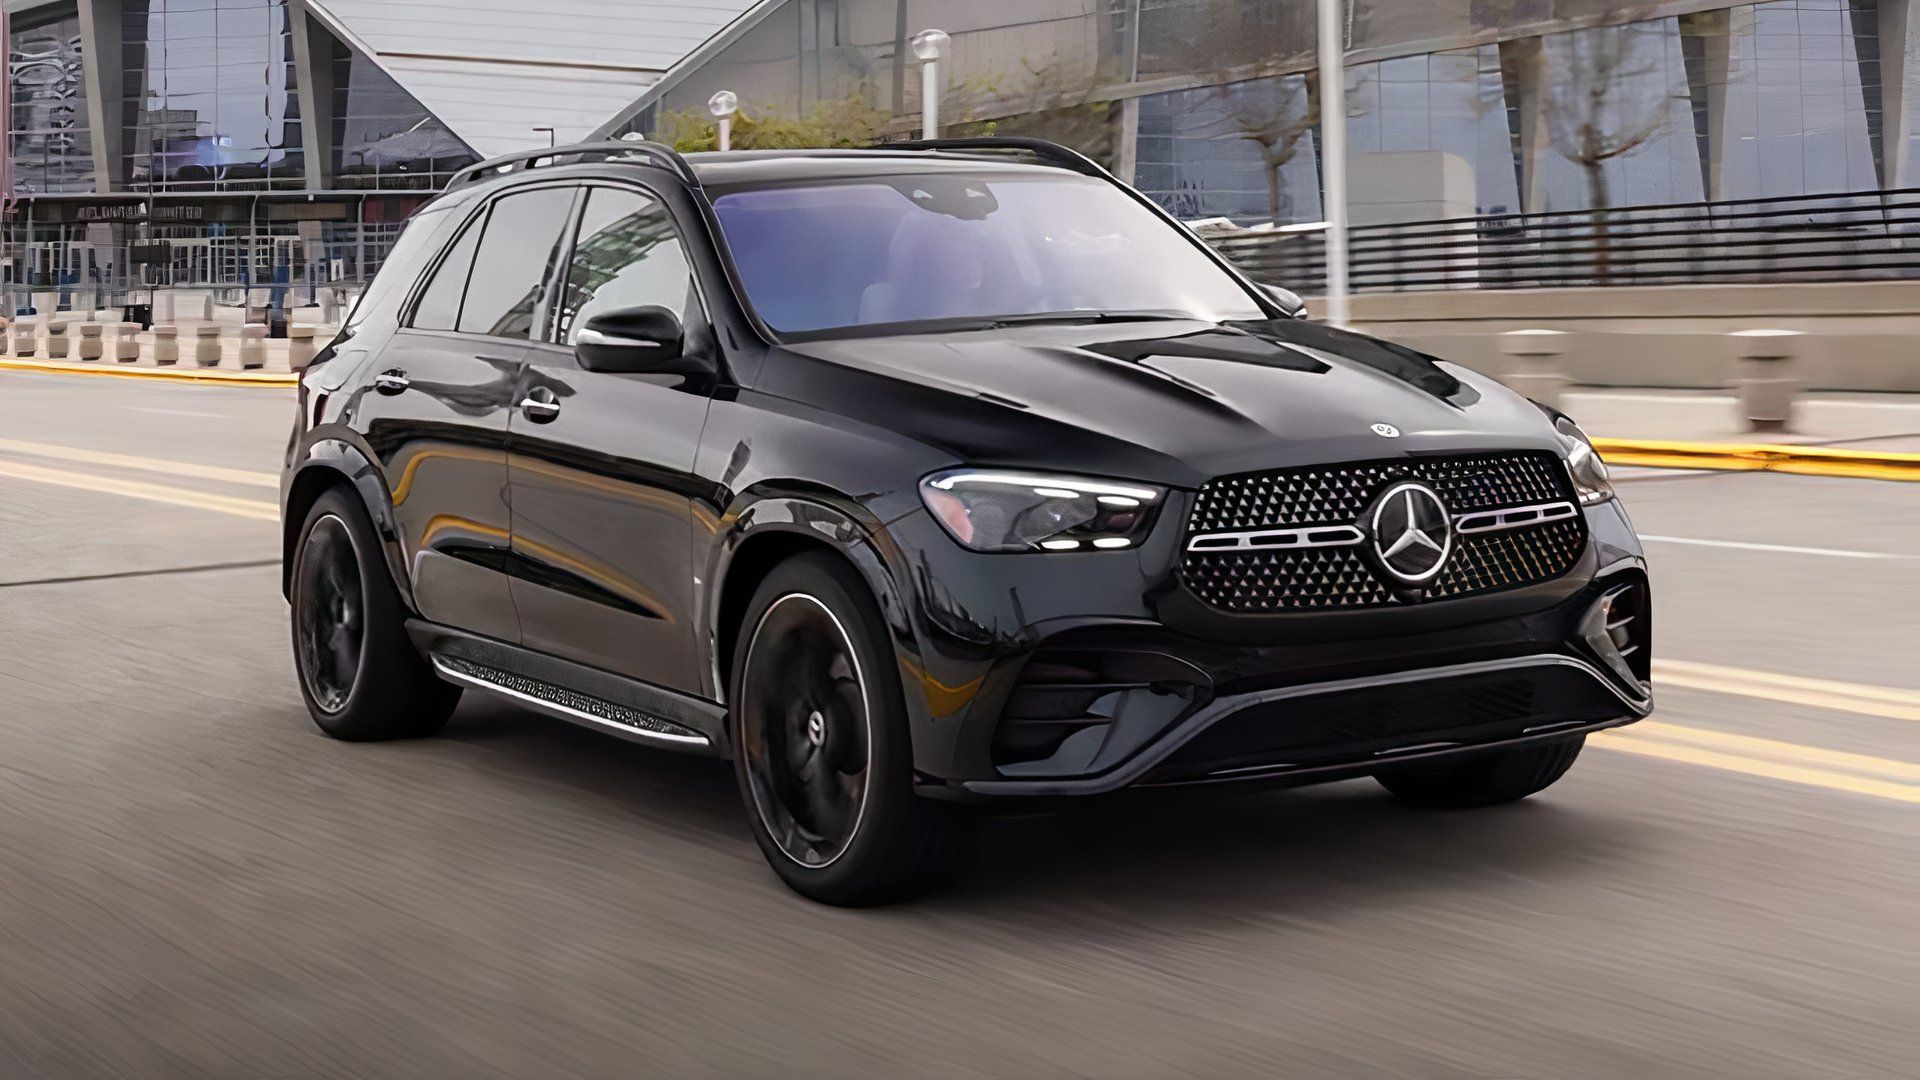
When you buy a luxury car, the transaction rarely starts with a handshake and a pile of cash. Instead, it relies on a sophisticated financial engine working behind the scenes. Mercedes-Benz Financial Services operates as the captive finance arm of the Mercedes-Benz Group, structured to turn high-end vehicle aspirations into structured monthly agreements. Rather than acting as a standard bank, this division coordinates everything from retail loans to corporate fleet logistics and digital account management.
Understanding how this financial infrastructure functions sheds light on how luxury automakers maintain market dominance and customer loyalty. It is not just about lending money; it is about designing an entire ecosystem that keeps drivers moving from one model to the next.
Core Financial Products for Retail Buyers
The retail side of the business caters to individual drivers who want structured paths to vehicle ownership or regular upgrades. Buyers generally choose between traditional retail financing and specialized leasing structures.
Traditional retail loans provide a straightforward route to permanent ownership. Customers secure a loan for a term typically ranging from 24 to 84 months, making fixed monthly payments until the balance reaches zero. This path suits drivers who plan to keep their vehicles long-term and prefer equity accumulation.
Leasing programs target drivers who prefer trading cars every few years to enjoy updated cabin technology and safety features. Leases involve lower monthly payments because customers pay only for the vehicle's projected depreciation during the term—usually 24 to 36 months—rather than its full value.
Personal Contract Plans (PCP) combine elements of both approaches. A PCP features lower monthly payments similar to a lease, but at the end of the term, drivers face three distinct choices:
- Pay an optional final balloon payment to keep the car outright.
- Return the vehicle to the dealership with no further obligations.
- Use the car as a trade-in equity contribution toward a new Mercedes-Benz.
Corporate Fleet and Commercial Financing
Beyond individual showroom buyers, commercial clients require entirely different scaling metrics. Businesses, executive transport companies, and public fleets rely on Mercedes-Benz Financial Services to manage vehicle inventory and operational costs.
Commercial packages often bundle vehicle acquisition with maintenance scheduling, insurance administration, and end-of-lifecycle disposal. Full Maintenance Packages (FMP) remove repair cost unpredictability by wrapping servicing fees into a single monthly invoice. This allows logistics managers and corporate executives to forecast transport budgets accurately while avoiding unexpected capital expenditures.
Dealer inventory financing forms another pillar of the commercial architecture. Authorized dealerships utilize wholesale credit lines to maintain diverse showroom stocks. This ensures that local lots display the latest electric and combustion models without straining franchise cash flow.
Evolution into Digital and Shared Mobility
Consumer habits have shifted away from traditional car ownership models, prompting financial institutions to adapt. The modern approach to transportation emphasizes access over possession, especially in dense urban environments.
Digital transformation has streamlined account management. Drivers handle credit pre-approvals, contract reviews, monthly auto-pay setups, and lease-end renewals through online portals and mobile applications. This reduces friction at the dealership level, matching the digital convenience expected from a luxury brand.
Shared mobility initiatives and car-sharing joint ventures address sporadic urban transport needs. By supporting platforms where multiple users access a pool of premium vehicles via smartphone apps, the parent group maximizes asset utilization while introducing younger demographics to the brand.
Common Pitfalls in Luxury Auto Financing
Navigating luxury vehicle finance requires careful attention to detail. Buyers frequently encounter financial friction points that can increase total ownership costs if ignored.
- Ignoring Mileage Restrictions on Leases: Exceeding annual mileage caps specified in a lease agreement triggers heavy penalty fees per extra mile at contract termination. Drivers must estimate their yearly driving habits accurately before signing.
- Overlooking End-of-Term Wear Guidelines: Returning a leased vehicle with interior stains, body dents, or non-genuine replacement parts leads to unexpected wear-and-tear charges. Regular maintenance through authorized service centers prevents these penalties.
- Focusing Solely on Monthly Payments: Extending loan terms past 72 or 84 months lowers monthly obligations but increases total interest paid and risks negative equity where the loan balance exceeds the vehicle's market value.
For official corporate guidelines and regional financial structures, consult the Mercedes-Benz Group Company Portal. To explore specific purchasing configurations and current regional promotional rates, visit the Mercedes-Benz Official Site.
Frequently Asked Questions
Can I buy out my Mercedes-Benz lease early?
Yes, you can terminate or buy out a lease before the scheduled maturity date. Doing so requires requesting an official payout quote, which includes the remaining depreciation balance, the residual value, and any applicable early termination fees specified in your contract.
What credit score is needed to qualify for financing?
Luxury tier financing typically requires a strong credit profile, generally starting in the good to excellent range (700 and above). Applicants with high credit scores secure the most competitive interest rates and favorable promotional terms offered through the manufacturer's finance division.
Are maintenance packages included in standard finance contracts?
Standard retail finance loans do not include maintenance costs. However, buyers and lessees can purchase prepaid maintenance plans or wrap service packages into their monthly lease agreements to cover scheduled upkeep at authorized dealerships.
How do corporate fleet programs handle vehicle disposal?
At the end of a commercial contract, the finance division manages asset disposal through trade-in buybacks, secondary auction channels, or lease returns. This frees corporate fleet operators from the burden of reselling used commercial vans and luxury sedans.



