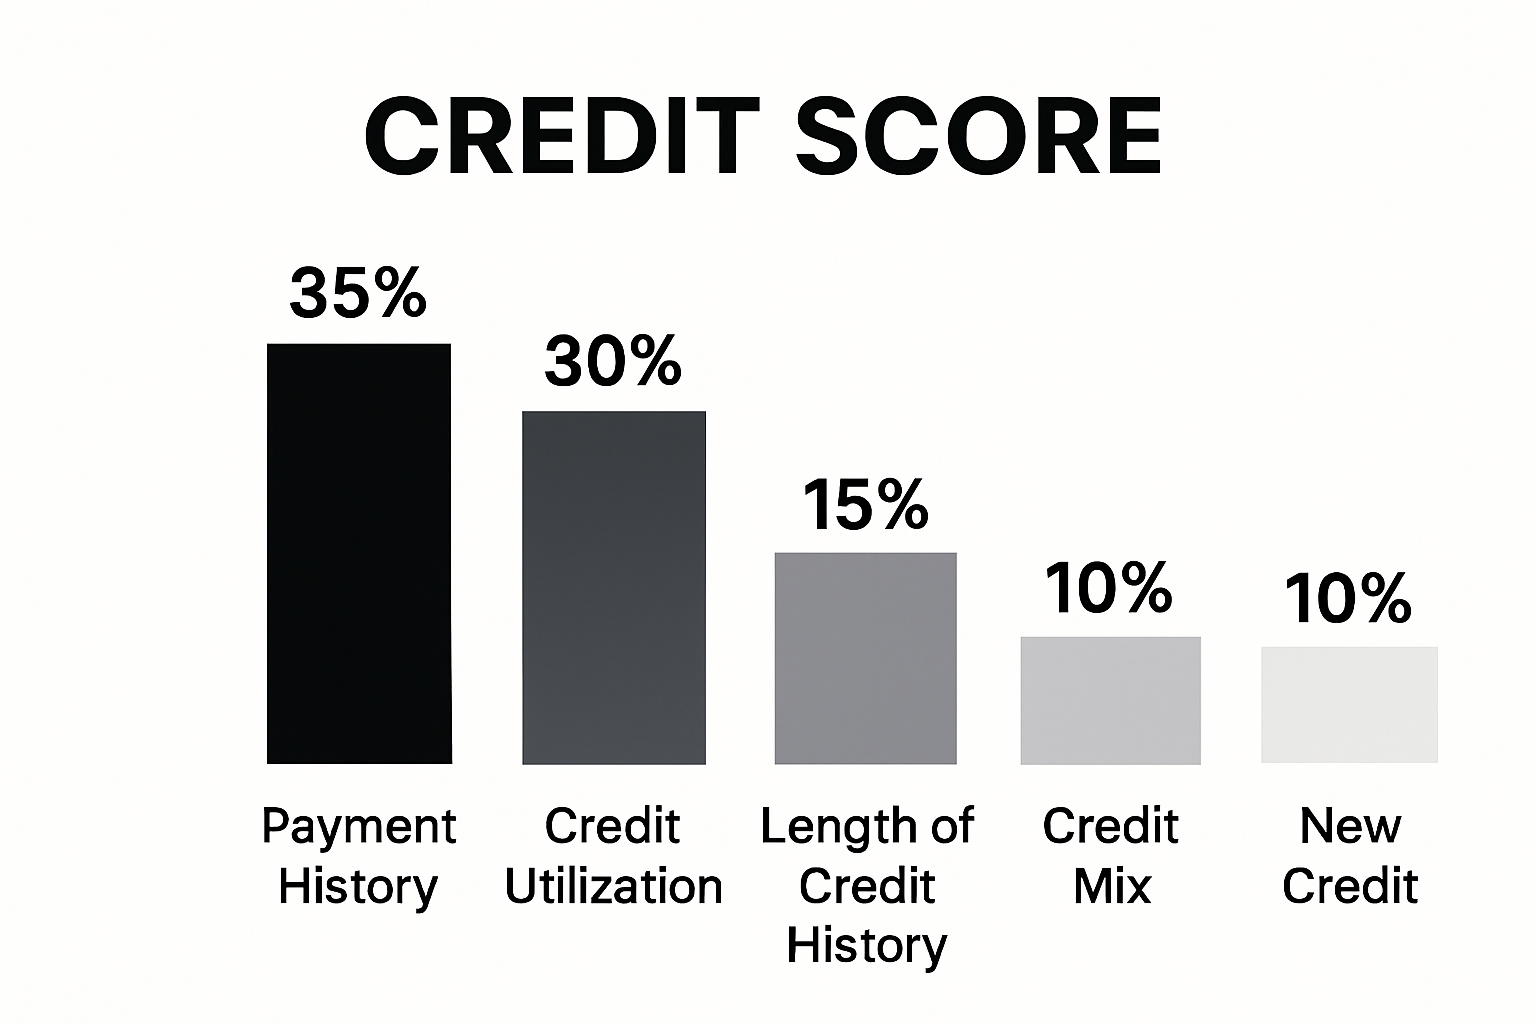
When a sudden job loss, medical emergency, or economic downturn hits your household, your credit score is often the first casualty. Bills pile up, accounts slip past due, and collections calls start ringing. Credit defense is the active process of safeguarding your credit history, disputing inaccuracies, and utilizing legal consumer rights to stop financial damage from spiraling out of control when you're most vulnerable.
Far from being a generic catchphrase, credit defense relies on statutory protections like the Fair Credit Reporting Act (FCRA). It gives you the legal tools to demand verification for every negative mark, correct reporting errors, and prevent predatory collectors from destroying your financial standing while you stabilize your income.
Understanding Credit Defense in Financial Hardship
Financial distress alters your day-to-day priorities. Rent, groceries, and utilities take precedence over credit card payments. Unfortunately, lenders and major bureaus (Equifax, Experian, and TransUnion) don't pause their reporting cycles just because you're going through a crisis. Within thirty to sixty days of missed payments, derogatory marks hit your report, tanking your score by a hundred points or more.
Credit defense acts as a legal shield during this chaos. It ensures that the information damaging your financial reputation is completely accurate, legally verifiable, and compliant with consumer protection laws. If a collection agency or creditor cannot legally prove you owe a specific balance with signed documentation, federal law requires them to remove the tradeline. To understand the full picture, check out the recent article by The New York Times.
Why Standard Advice Fails During a Crisis
Most mainstream financial advice tells you to "just pay your debts on time" or "keep a six-month emergency fund." That advice is useless when you're already facing an active crisis and your savings are gone.
Credit defense shifts the focus from passive panic to tactical defense. Instead of letting automated collection systems dictate your financial future, you exercise your right to audit the data collectors and dispute unverified claims.
The Core Pillars of Effective Credit Defense
Building a solid defense requires a structured approach. You don't need expensive credit repair agencies; you can manage these steps yourself with organization and persistence.
1. Secure and Audit Your Credit Reports
You can't defend what you can't see. Pull your official credit reports for free through Annual Credit Report, the federally authorized source.
- Look closely at collection accounts, late payment markers, and charged-off balances.
- Check for duplicate collection entries where the same debt was sold to multiple agencies and reported twice.
- Verify personal identifying information, as mixed files due to similar names frequently occur during high-stress economic periods.
2. Issue Formal Verification Demands
Under the Fair Debt Collection Practices Act (FDCPA), you have the right to request written validation of any debt within thirty days of first contact from a collector.
- Send your request via certified mail with a return receipt requested.
- Do not acknowledge ownership of the debt over the phone.
- Require the collector to provide the original signed contract, a complete accounting of fees, and proof that they own the debt. If they fail to provide this, they must legally cease collection activity.
3. Dispute Inaccuracies with the Bureaus
If credit bureaus are reporting false or unverified negative data, file formal disputes directly with Equifax, Experian, and TransUnion.
- Clearly identify the specific account in question.
- State the exact reason for the dispute (for example, "balance is inaccurate" or "account does not belong to me").
- Attach supporting documents, such as bank statements or letters from original creditors, but never send original paperwork.
Common Credit Defense Mistakes to Avoid
When panic sets in, it's easy to make moves that worsen your credit standing. Avoid these critical errors:
- Ignoring collection notices: Ignoring letters won't make collectors go away; it often leads to default judgments, wage garnishments, and severe credit score drops.
- Settling without written agreements: If you negotiate a pay-for-delete or settlement amount, get the terms in writing before sending a single dollar. Verbal promises from collection agents are rarely honored.
- Closing your oldest accounts: Even if an older credit card has a zero balance or low limit, closing it shortens your credit history length and increases your overall utilization ratio.
- Relying on unauthorized credit repair scams: Avoid any company that guarantees a 100-point score increase in thirty days or asks for upfront monthly fees before rendering services.
Frequently Asked Questions
Can credit defense stop collection lawsuits?
While credit defense focuses primarily on your credit reports and debt verification, invoking your FDCPA rights and demanding debt validation often halts aggressive collection cycles before they escalate to civil court. If you are served with a lawsuit, you must respond in court, as ignoring a legal summons results in an automatic default judgment.
How long do disputed negative items take to disappear?
By law, credit bureaus have thirty days (or forty-five days in certain specific circumstances) to investigate a dispute once they receive it. If the creditor cannot verify the information within that window, the bureau must remove or correct the entry.
Does disputing a debt hurt my credit score further?
No. Simply filing a dispute or requesting debt validation does not lower your credit score. In fact, if the bureau removes an unverified negative mark as a result of your dispute, your score can recover significantly.
What should I prioritize when I can only pay some of my bills?
Prioritize shelter, utilities, and basic food needs first. Secured debts like mortgages and auto loans come next because default leads to immediate repossession or foreclosure. Unsecured credit cards and personal loans fall to the bottom of the priority list during an acute crisis, as they carry no immediate physical collateral risk.



