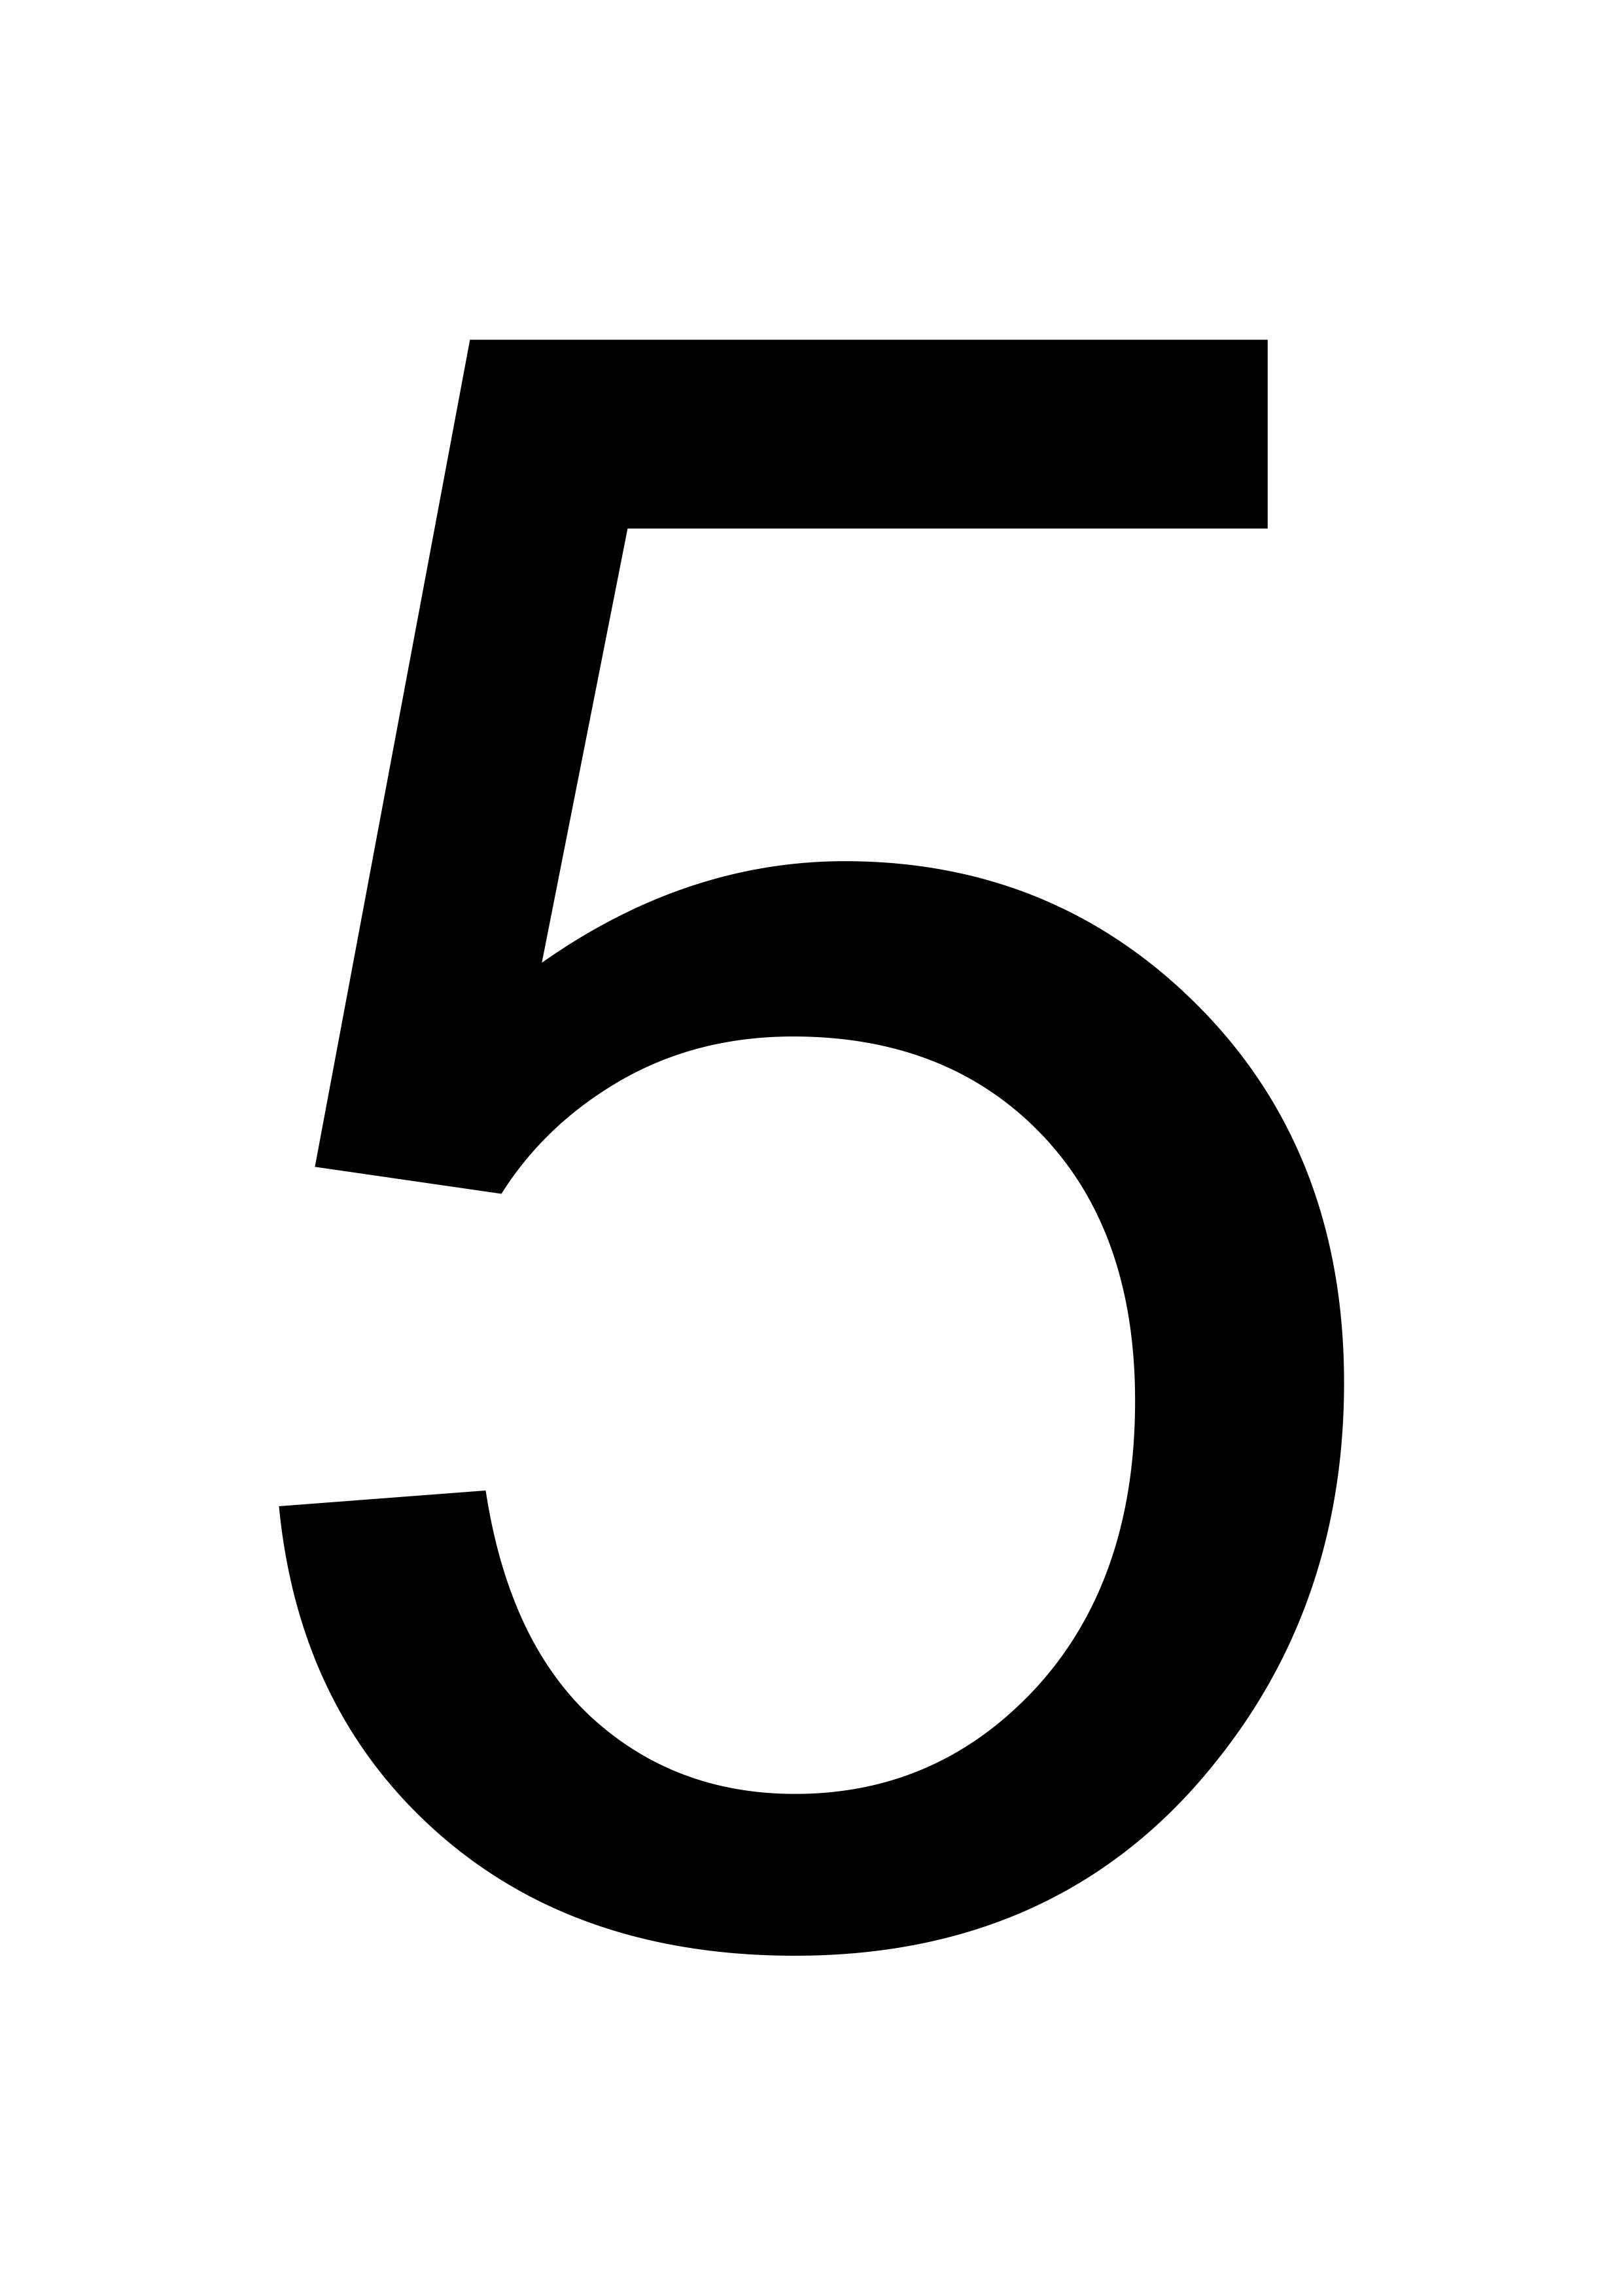
Converting 5,000 Philippine pesos to US dollars requires looking past basic web calculators to understand real-world transfer fees, exchange rate spreads, and timing strategies. At the current benchmark rate of approximately 0.0158, 5,000 PHP converts to roughly $78.92 USD. However, what lands in your recipient bank account or digital wallet often differs because traditional banks and remittance services rarely pass along the exact mid-market rate without taking a cut.
Managing currency exchange efficiently demands a clear look at how commercial rates work, where hidden markups squeeze small transfers, and which transfer methods keep your purchasing power intact. Whether you're sending money to family, paying for overseas freelance services, or budgeting for an upcoming trip, small amounts like 5,000 pesos are particularly vulnerable to flat transfer fees that eat up a large percentage of the total principal.
Understanding the PHP to USD Exchange Rate Mechanics
Exchange rates fluctuate constantly based on macroeconomic factors, inflation differentials between the United States and the Philippines, central bank policies, and global market sentiment. The rate you see on financial news sites or search engine widgets is the mid-market rate—the midpoint between global buy and sell orders.
Retail consumers almost never get this exact rate. When you use a high-street bank or a traditional wire service, they apply a retail markup known as the exchange rate spread. If the true market rate is 0.0158, a traditional bank might quote you an effective rate of 0.0150, pocketing the difference while advertising zero transfer fees. On a 5,000 PHP transaction, that hidden markup quietly chips away at your total value before flat fees even enter the equation.
Spot Rates Versus Transfer Rates
Spot rates represent immediate currency trades settled on the spot market, which form the baseline for retail conversions. When you initiate an online transfer, you're usually locking in a transfer rate provided by a remittance provider. These providers hedge their currency inventory to offer a locked-in rate for a specific window, protecting you from sudden intraday volatility while baking in their operational margins.
Comparing Transfer Methods for 5,000 Pesos
Because 5,000 PHP is a relatively modest sum—roughly $79 USD—the method you choose dictates whether your recipient gets most of that money or loses half of it to fixed transaction costs. Fixed fees punish small transfers heavily.
Traditional wire transfers through legacy commercial banks often charge a flat fee ranging from $15 to $45, alongside unfavorable exchange rate markups. If you wire 5,000 pesos through a traditional bank, fixed fees alone can consume 20% to 50% of the transaction value.
Digital-first remittance platforms and multi-currency accounts have altered this landscape. Services like Wise and Remitly specialize in transparent pricing, splitting out the exact percentage fee and applying closer-to-market exchange rates. For smaller amounts, peer-to-peer networks or digital wallets often provide the most cost-effective path, provided you check both the upfront fee and the offered exchange rate simultaneously.
Practical Steps to Maximize Your Currency Conversion
Executing a cost-effective currency exchange requires methodical planning rather than rushing through the first available portal. Follow these actionable steps to protect your funds:
- Check the live mid-market rate on an independent financial tracking platform right before you initiate the transaction so you have a baseline for comparison.
- Compare at least three different providers by entering 5,000 PHP into their online estimation tools to see the exact final amount delivered in USD.
- Calculate the total cost by subtracting the delivered USD amount from what the raw mid-market conversion should yield, exposing both explicit fees and hidden rate markups.
- Choose the delivery speed that fits your timeline; faster delivery options like instant debit card funding usually carry slightly higher fees than slower bank-to-bank ACH transfers.
- Review the recipient payout method carefully, ensuring the receiving bank account or cash pickup location doesn't impose local intermediary fees upon arrival.
Common Mistakes to Avoid When Exchanging Pesos
Overlooking small details during international transfers leads to unnecessary financial leakage. Avoid these frequent pitfalls:
- Falling for zero-fee marketing: Providers advertising zero fees often compensate by padding the exchange rate spread heavily, making it far more expensive than a transparent service with a small upfront fee.
- Ignoring intermediary bank fees: Traditional SWIFT transfers can route through multiple intermediary banks, each skimming a small cut from the transfer before it reaches the final destination.
- Timing panic: Trying to time minor hourly fluctuations on a small amount like 5,000 pesos wastes time; the transaction cost usually outweighs any minor intraday currency swing.
- Neglecting account limits: Some digital wallets require identity verification upgrades to process cross-border transfers above specific thresholds, which can freeze your funds temporarily.
Frequently Asked Questions
How much is 5,000 Philippine pesos in US dollars?
At current market conditions, 5,000 Philippine pesos converts to approximately $78.92 US dollars, though actual amounts vary slightly depending on live market movements and provider markups.
Are traditional banks safe for small peso transfers?
Traditional banks offer high security, but they are generally inefficient for smaller amounts like 5,000 PHP due to high flat fees and poor exchange rates designed for large corporate wires.
Why do exchange rates differ between online platforms?
Different providers source their liquidity from various financial institutions and maintain distinct business models, funding some operations through upfront transfer fees and others through currency conversion markups.
Can I lock in an exchange rate in advance?
Many modern transfer platforms allow you to lock in a specific exchange rate for 24 to 72 hours while your funding transfer clears, protecting you from sudden currency drops.



